On 21 November 2026, Regulation (EU) 2024/1157 — the revised Waste Shipment Regulation — makes it illegal to export plastic waste from the EU to any non-OECD country. The ban is not a trial measure. It runs until at least 21 May 2029, and any country that wants EU plastic waste after that must apply, prove it can manage the material to European standards, and wait. For an industry that has quietly shipped roughly 500,000 to 800,000 tonnes of plastic waste a year out of Europe, the cheapest exit route closes in under three weeks. What replaces it is a question every waste manager, recycler, and packaging buyer on the continent now has to answer. Our short answer: a large share of that material — the mixed, grey, contaminated grades nobody wants — is exactly what compression-molded pallet production was built to absorb.

What the ban actually changes
The details matter, because a lot of wishful thinking is circulating about workarounds. The European Commission’s own plastic waste shipments guidance lays out the sequence. Since 21 May 2026, all plastic waste exports — even clean, non-hazardous B3011 material bound for recycling — require the prior notification and consent procedure. Both the exporting and the receiving authority must sign off before a container moves. From 21 November, exports to non-OECD destinations stop entirely.


Exports to OECD countries continue, but under the same notification regime, and with a monitoring threat hanging over them. The Commission just published an assessment of plastic waste flows to Türkiye, the main OECD destination. In 2025, Türkiye took 510,000 tonnes of EU plastic waste — over a third of the EU’s total plastic waste exports. The report acknowledges improvements in Turkish legislation and enforcement while flagging limited transparency, unclear implementation, and stakeholder concerns about actual harm on the ground. Campaigners called the decision to let flows continue a troubling gap between the Commission’s evidence and its interpretation. Either way, the direction of travel is obvious: every destination is getting harder, and none is guaranteed.
The arithmetic nobody has solved
Here is the uncomfortable part. The EU generates around 40 million tonnes of plastic waste a year and exports between 1 and 1.5 million tonnes of it, split roughly half to OECD and half to non-OECD countries. When the ban lands, an estimated 500,000 to 800,000 tonnes per year must find treatment inside Europe. That volume was never exported because European plants wanted it. It was exported because European plants would not take it.
The domestic capacity picture is not encouraging. EU recycling capacity stood at roughly 13.2 million tonnes in 2023, and around one million tonnes of it — the equivalent of France’s entire capacity — was shut down by the end of 2025, priced out by cheap virgin polymer and weak demand. Plastics Europe’s own numbers show circular production growth slowing from 13.6% in 2022 to 1.2% in 2024, with circular output stuck at 8.7 million tonnes. As industry reporting has noted, as long as a shipping container to Southeast Asia cost less than a European sorting line, nobody built the sorting line. Now the shipping container option is gone, and the sorting lines were never built.
There is a real risk the ban simply pushes material toward incineration and landfill for a couple of years. Bale markets have already started behaving strangely. Argus tracked Northwest European flexible PE bale prices falling about 17% in a single two-month window when export disruption hit, and traders have been front-loading shipments all year ahead of the deadline. The transition will be messy before it is profitable.
Why molded pallets are the pressure valve
Not all stranded material is equal, and this is where the opportunity hides. Look at recycled polymer pricing and one gap jumps out. At the end of June 2026, natural rHDPE pellets traded around €1,705–1,715 per tonne in Northwest Europe, while grey rHDPE sat at €1,111–1,121. Black rPP pellets were down to €960–970. The colour gap between natural and grey rHDPE is roughly €600 per tonne — more than the entire price of black rLDPE. The polymer is chemically the same. What differs is the sorting burden upstream, and that €600 is the market’s price for purity.
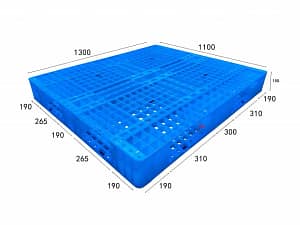
Grey and mixed grades are confined to applications that tolerate them: pipes, technical parts, and — consistently named in every market commentary — pallets. Pallets do not care that the material is grey. They care about stiffness, impact resistance, dimensional stability, and price per unit. A compression molding line takes crushed flakes of mixed PP and PE straight into the extruder and the press, with no washing, no pelletizing, and no pellet-grade specification to defend. Trade reports from Asian line builders working with difficult feedstocks — cable skin, woven bags, municipal mixed rigid — point to blend ratios around 40–50% rigid PP/PE mixed into the stream to restore rigidity and load capacity, set by testing on the customer’s actual material rather than a datasheet. That flexibility is precisely what a pelletizing-based recycling chain cannot offer when the input is unpredictable.
The demand side is real, too. Japan’s Gifu Plastics Industry just launched a one-way logistics pallet made of 100% recycled PP, weighing 4.9 kg in a 1100×1100 mm footprint, with 500 kg dynamic and 1,000 kg static load — released to market in November 2026, driven by resin cost inflation and Japan’s revised logistics efficiency law. India’s municipal procurement is following the same track; Nashik’s municipal corporation has a live tender for molded plastic pallets for pharmacy stores and warehouses. And PPWR’s recycled-content obligations, fully biting from 2030, are slowly converting recycled plastic from a cost decision into a compliance decision across European packaging supply chains.
If you run — or plan — a molded pallet line, what now
For producers in the EU, Türkiye, and the neighbouring markets that have been living off exported bales, the next two years will decide who owns the domestic feedstock relationships. Three checks are worth doing before anyone signs an equipment order.
First, audit the waste you can actually get. The stranded volumes are mixed and contaminated by definition. The question is not “is there plastic waste nearby” but “who pays whom to move it today.” A site collecting industrial mixed polyolefin waste that currently pays €80–120 per tonne in gate fees has, in effect, negative-cost feedstock once that waste has nowhere else to go. That flips the usual economics of recycled pallet production.
Second, test before you buy. Blend behavior, moisture tolerance, and flow characteristics of genuinely dirty feedstock cannot be read off a catalogue. Any responsible line supplier will run your actual material — crushed flakes, cables, film scraps — and return a report with the blend recipe and the pallet load results. If a supplier quotes you from a brochure, walk away.
Third, run the capacity math honestly. A 1,600–1,800 ton hydraulic press running 15–20 pallets per hour produces roughly 250–300 molded pallets per shift, and at 18–25 kg per pallet that consumes 5–7 tonnes of feedstock daily. Sustaining that requires contracted waste streams, not opportunistic spot buys. Our plastic pallet molding machine page breaks down the full line architecture — shredding, extrusion, dosing, pressing, demolding — for exactly this kind of feedstock-first planning.
A closing note of caution
The ban will not create a smooth, rising tide for recyclers. In the short run, more supply chasing weak demand means lower bale prices and pressure on anyone selling commodity recyclate. The winners will be operations that convert cheap, ugly feedstock into a product with its own demand — and molded pallets, with their tolerance for mixed material and their structural, non-cosmetic specification, sit in the sweet spot. Three weeks from now, Rotterdam loses one of its steadiest outbound cargoes. The factories that treat that cargo as tomorrow’s raw material, instead of this year’s problem, will be the ones still profitable when the market reopens in 2029 — if it ever reopens on the old terms.